



How a 2% Deductible Can Mean $8,000 Out of Pocket in Minnesota

Most Minnesota homeowners policies now carry a separate wind or hail deductible, and it’s usually a percentage of your dwelling coverage rather than a flat dollar figure. Pull your declarations page today, photograph any visible damage, and call your agent or South Lake Agency to confirm which deductible actually applies to your roof.
TL;DR:
Minnesota homeowners with percentage wind and hail deductibles could face out-of-pocket costs up to 20,000 dollars for a 400,000-dollar home if a 5% deductible applies.
Insurers typically apply wind and hail deductibles once per storm event, meaning multiple damages from a single storm only require one deductible payment.
Legal protections in Minnesota prevent contractors from waiving deductibles and enforce coverage for code-required repairs, especially on older roofs.
Filing a claim is worthwhile only if the repair costs exceed the deductible by a sizeable margin, as small payouts may not justify premium increases.
An independent broker can review policies for actual dollar exposure, shop for better terms, and help prevent homeowners from being surprised by rising deductible costs.
Table of Contents
How Minnesota Insurers Calculate Your Wind Hail Deductible
Two structures show up on Minnesota policies, and the difference between them can swing your out-of-pocket cost by thousands of dollars. A flat-dollar deductible is a fixed number, say $1,000 or $2,500, regardless of what your home is worth. A percentage-based wind hail deductible, by contrast, is calculated against your dwelling coverage limit, not the cost of repairs. That distinction catches a lot of homeowners off guard when a claim comes in.
Here’s what that looks like in real dollars:
A 1% deductible on a $400,000 home equals $4,000 out of pocket.
A 2% deductible on a $400,000 home equals $8,000 out of pocket, a figure the Horton Group’s wind and hail explainer uses as a standard illustration.
A 5% deductible on a $400,000 home equals $20,000 out of pocket.
Insurers in storm-exposed states like Minnesota lean on percentage deductibles because flat $1,000 deductibles don’t scale with claim frequency or rebuilding costs. Hail season hits Minnesota hard enough, and often enough, that carriers price the risk into a variable deductible instead of a fixed one. The Minnesota Department of Commerce has flagged this shift directly, warning that insurers increasingly separate wind and hail deductibles from the standard policy deductible, sometimes without homeowners noticing until a claim is already underway.
How Your Claim Payout Actually Gets Calculated
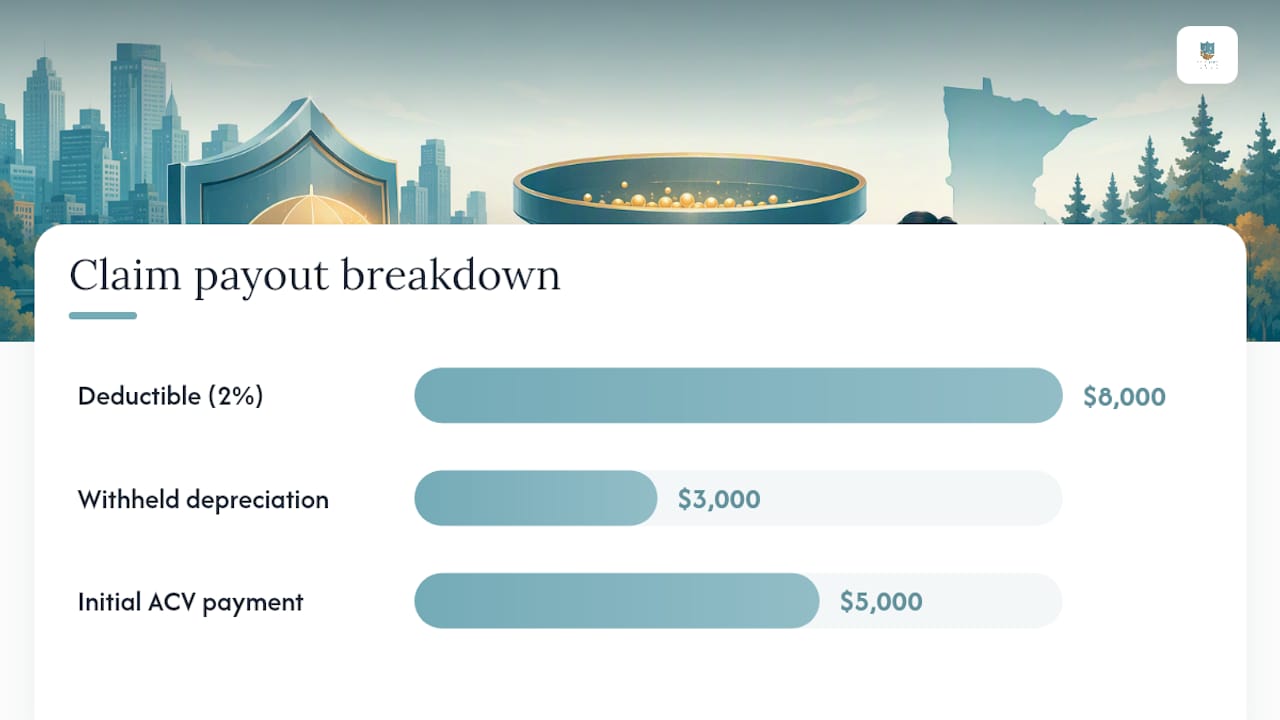
Insurers pay in two steps if your policy carries replacement cost coverage, and understanding the sequence keeps you from panicking over a smaller-than-expected first check. You’ll receive an actual cash value (ACV) payment first, which subtracts both your deductible and depreciation for the age and condition of your roof. The remaining depreciation, called recoverable depreciation, gets released only after you complete the repairs and submit proof.
Here’s how the math typically plays out on a $16,000 roof claim with a 2% deductible on a $400,000 dwelling:
Total repair estimate: $16,000
Deductible ($8,000) and depreciation withheld ($3,000) subtracted, leaving an initial ACV check of $5,000
After the roof is replaced and receipts submitted, the insurer releases the $3,000 in withheld depreciation
Wind and hail deductibles apply once per storm event, not once per trade. If a single hailstorm damages your roof, siding, and gutters, you pay the deductible one time against the combined claim, according to Owl Roofing’s claim guidance for Minnesota homeowners. That’s exactly why getting every damaged trade scoped into one claim matters. Splitting repairs into separate mini-claims can trigger the deductible more than once and cost you real money.
Minnesota Law and Court Rulings That Shape Your Claim
Minnesota’s legal framework does more to protect homeowners than most people realize, but only if you know it exists. The Minnesota Department of Commerce has issued a consumer alert noting that complaints about wind and hail coverage changes rose nearly 20% since 2020, largely tied to insurers introducing separate percentage deductibles at renewal without clear notice.
Minnesota Statutes back this up with specific language. Minn. Stat. §65A.27 defines the scope of homeowner policies and the replacement-cost obligations tied to them, and the Minnesota Supreme Court has weighed in on how far those obligations extend.
In interpreting Minn. Stat. §65A.10, the Minnesota Supreme Court held that replacement-cost insurers may need to cover code-required work, such as new roof sheathing, when that work is necessary to properly replace the storm-damaged portion of the home.
That’s the practical effect of the Campbell decision, as summarized by Zelle Law. It matters most on older roofs, where code compliance often forces extra decking work insurers might otherwise try to exclude.
One more protection worth knowing:
Minnesota contractors are legally barred from waiving, absorbing, or paying any part of your deductible under Minn. Stat. §325E.66.
Accepting a deductible-waiver offer can lead to claim denial, policy cancellation, or criminal exposure for both parties.
Should You Even File the Claim? Do This Math First
Before you call your insurer, run the numbers. A claim that barely clears your deductible often isn’t worth filing once you factor in future premium increases.
Get a written repair estimate from a licensed contractor.
Subtract your dollar deductible (not the percentage, the actual dollar figure from your declarations page) from that estimate.
If the remainder is small relative to your deductible, weigh the cost of a rate increase against the payout.
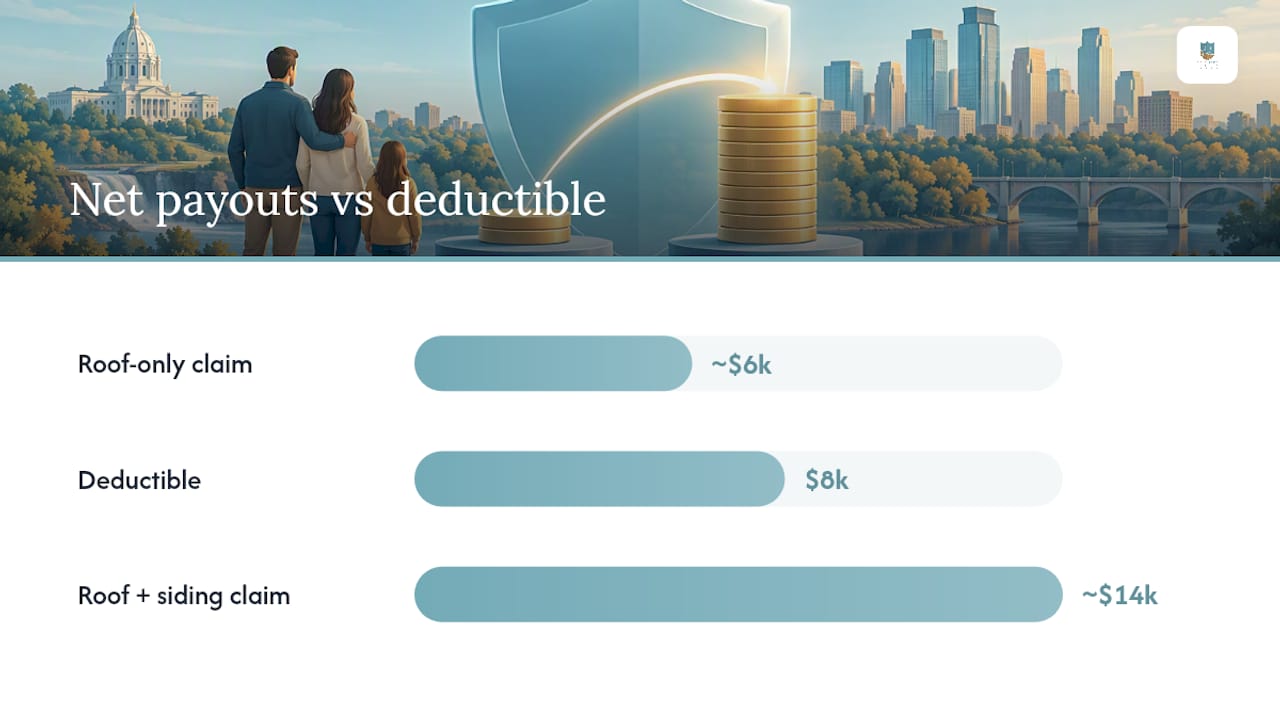
Three quick scenarios: a roof-only claim near $14,000 against an $8,000 deductible nets you roughly $6,000, likely worth filing. A roof-plus-siding claim near $22,000 against the same deductible nets $14,000, clearly worth it. A cosmetic-only hail claim, denting gutters without functional damage, may fall under policy exclusions entirely, so check your language before you file.
Pro Tip: Get the contractor inspection before you call your insurer, not after. A full trade scope, roof, siding, gutters, windows, in one estimate keeps your deductible from applying more than once.
What to Do in the First 72 Hours After a Storm
Move fast, but move in the right order. Evidence collected in the first three days often determines how smoothly your claim goes from here.
Photograph all visible damage from the ground, and note the date, time, and storm conditions.
Call your insurer immediately to open a claim, then write down your claim number and adjuster’s name and phone number.
Schedule a licensed Minnesota contractor inspection before any repairs begin, and have that contractor attend the adjuster meeting if possible, a step local restoration guidance consistently recommends.
Keep every receipt for emergency tarping, board-up work, or temporary lodging.
Refuse any contractor who offers to waive or cover your deductible. It’s illegal, and it puts your entire claim at risk.
Why an Independent Minnesota Broker Matters Here
A single-carrier agent can only tell you what one insurer’s policy says. An independent broker can pull your declarations page, calculate your actual dollar exposure under a percentage deductible, and shop that risk across multiple carriers to find better terms.
That’s the core of what South Lake Agency Insurance Brokers does for Minnesota homeowners:
Reviews your current declarations page and translates the percentage deductible into a real dollar figure.
Shops coverage across more than 20 carriers to find better wind/hail terms.
Coordinates directly with your claims adjuster and, when buying a new home, your lender or title company.
Reach out when your claim involves multiple trades, your deductible language feels unclear, or you’re unsure whether your current carrier still fits your risk after a bad storm season.
An Editorial Take on Minnesota’s Hail Math
Minnesota gets hit by enough severe hail that insurers have quietly rewritten the deductible rules over the last several years, and most homeowners don’t notice until they’re standing in a damaged living room reading their policy for the first time. That’s backwards. The declarations page should get the same annual attention as your furnace filter.
Check it every renewal, before the storm, not after.
— Andrew
Get Your Wind Hail Deductible Reviewed Before the Next Storm
If you’ve read this far, you probably already suspect your deductible is higher than you think. An independent insurance broker can review your current homeowners policy, calculate your actual dollar exposure under a percentage wind/hail deductible, and shop coverage options across multiple carriers without charging a broker fee.
Have your current declarations page, any recent home appraisal, and photos of existing roof condition ready when you reach out. If you’ve already gotten a contractor estimate for prior damage, bring that too. It helps identify gaps in your current coverage faster. Start your review today by comparing homeowners insurance quotes, or explore the new homebuyer insurance guide if you’re closing on a house this year. For related coverage questions, our guide on roof replacement coverage and general advice on insurance during renovation are worth a read too.
Sources
FAQ
What Is a Good Wind Hail Deductible in Minnesota?
Run your own dollar math against your declarations page rather than relying on a generic benchmark.
Do You Have to Pay Your Deductible if You Have Hail Damage?
Yes. The deductible is subtracted from your claim payout before you receive any check, and Minnesota contractors are legally barred from waiving or covering it under Minn. Stat. §325E.66. Accepting an offer to skip your deductible can lead to claim denial or worse.
Is It Better to Have a $500 Deductible or a $1,000 Deductible?
A lower deductible means smaller out-of-pocket costs per claim but usually higher premiums year-round, while a higher deductible lowers your premium but increases what you owe if a storm hits. Most Minnesota homeowners with a separate wind/hail deductible are working with a percentage figure anyway, which often dwarfs either flat option.
Why Is My Wind Hail Deductible So High?
Insurers in hail-prone states like Minnesota shifted toward percentage-based deductibles because flat deductibles didn’t keep pace with the frequency and cost of storm claims. The Minnesota Department of Commerce has noted rising complaints tied to this shift, particularly when it happens quietly at renewal.
Can a Broker Help Lower My Wind Hail Deductible Costs?
An independent broker can’t change state weather patterns, but an independent broker can shop your policy across multiple carriers to find better deductible terms or premium tradeoffs suited to your risk. Compare options through their homeowners insurance quotes page.
Recommended
Comments