



Telematics Car Insurance: Worth It for Safe Drivers?

Telematics car insurance is worth it if you’re a low-mileage driver with clean habits behind the wheel. The trade-off is straightforward: you trade continuous monitoring of your driving, and sometimes your location, for a shot at a lower premium. The median payoff isn’t dramatic. Consumer Reports found the median annual savings among telematics users lands around $120, which matters less than whether you’re comfortable with an insurer watching how, when, and sometimes where you drive.
That’s the whole calculation in one sentence: modest, real savings for most people, bigger savings for a smaller group of very safe drivers, and a data-sharing relationship you should understand before you agree to it.
Pro Tip: Before you enroll in any program, ask your insurer directly whether the app or device can be turned off mid-trip and whether declining it after signup resets your discount clock to zero.
Quick gut-check before you read further:
If you drive relatively few miles a year, mostly during daylight, telematics insurance can often result in savings.
If you drive for work, at night, or across long highway stretches regularly, the math often works against you.
If GPS tracking of your daily routes bothers you, ask specifically whether location data is optional. It sometimes is.
Key Takeaways
Telematics car insurance rewards low-mileage, safe drivers with modest savings while requiring them to accept ongoing monitoring of driving behavior and sometimes location.
Point | Details |
Savings are real but modest | Median annual savings sit around $120, well below many advertised “up to 30%” discounts. |
Monitoring takes months | Most programs need 60 to 90 days or longer before any rate adjustment applies. |
Privacy risk is the trade-off | Location and behavior data can sometimes be shared or sold in de-identified form, so ask before enrolling. |
Rates can rise, not just fall | Risky measured behavior during monitoring can increase your premium instead of lowering it. |
A broker compares programs for you | South Lake Agency Insurance Brokers shops telematics offers across 20+ carriers with no broker fees, helping you match the right program to your actual driving profile. |
Table of Contents
Program Types: Pay-Per-Mile, Pay-How-You-Drive, and Hybrid Models
How to Enroll, How Long Monitoring Lasts, and Whether You Can Opt Out
How an Independent Broker Helps You Evaluate Telematics Programs
Author Perspective: Honest Pros and Cons From a Broker’s Viewpoint
How South Lake Agency Can Help You Evaluate Telematics Options
What Is Telematics Car Insurance and How Does It Work?
Telematics ties your premium to how you actually drive instead of relying only on age, credit-based scoring, or zip code. It’s also called usage-based insurance, or UBI, and you’ll see it marketed under names like pay-as-you-drive, pay-how-you-drive, or pay-per-mile depending on the carrier. The Insurance and Risk Management Institute defines UBI as pricing that aligns cost with time, distance, behavior, and place, adjusting dynamically instead of resetting once a year at renewal.
Three types of hardware do the actual data capture. A smartphone app uses your phone’s accelerometer and GPS chip, which is the cheapest option for insurers to deploy and the easiest for you to install, though it can misattribute passenger-seat driving to you if you forget to switch profiles. An OBD-II plug-in device connects directly to your car’s diagnostic port and reads engine and braking data straight from the vehicle rather than a phone, which usually produces cleaner readings but requires you to physically install and later return hardware. Embedded telematics, built into the car by the manufacturer, is increasingly common in newer vehicles and needs no separate app or plug-in at all.
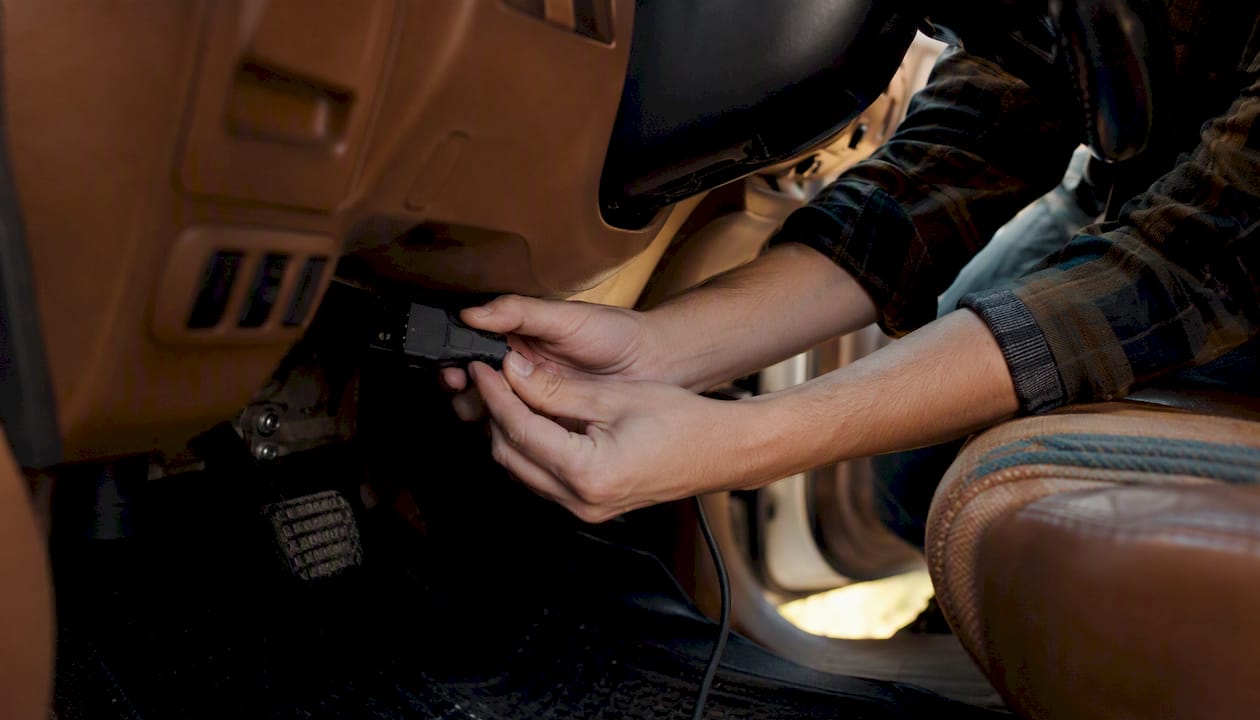
Whichever method your insurer uses, the data flow is the same: your device captures raw driving events, an algorithm scores those events against a risk model, and the insurer applies that score to your next billing cycle or renewal. The National Association of Insurance Commissioners notes that most programs need several months of monitoring before enough data exists to calculate a meaningful adjustment.
Device Type | Accuracy | Convenience | Typical Data Captured |
Smartphone app | Moderate (can confuse driver vs. passenger) | High, no installation | Speed, braking, phone handling, GPS |
OBD-II plug-in | High, reads vehicle systems directly | Moderate, requires install/return | Speed, acceleration, braking, engine data |
Embedded (OEM) | High, factory-integrated | Highest, nothing to install | Speed, braking, mileage, sometimes location |
Program Types: Pay-Per-Mile, Pay-How-You-Drive, and Hybrid Models
Not all usage-based insurance measures the same thing, and picking the wrong mental model leads to bad expectations. Pay-as-you-drive (PAYD) programs price your policy mainly on how many miles you log, treating a low annual mileage count as inherently lower risk. Pay-how-you-drive (PHYD) programs ignore mileage almost entirely and instead score braking harshness, acceleration, cornering, and time-of-day patterns. Pure pay-per-mile products, meanwhile, aren’t really behavior-based at all. NerdWallet notes only a handful of insurers offer true per-mile pricing, and some of those still require a monthly odometer photo rather than a connected device.
The practical difference shows up in your bill. PAYD programs often adjust your base rate at renewal once mileage data accumulates. PHYD programs can shift a discount monthly as your driving score updates. Hybrid models, which most major telematics apps run today, blend both: a mileage baseline plus a behavior modifier layered on top.
A retired commuter driving 4,000 miles a year fits PAYD best, since low mileage alone earns most of the discount.
A cautious driver who sticks to short errands but drives frequently benefits more from PHYD, since good habits get rewarded regardless of total distance.
Someone with a second car that sits mostly parked is the classic case where pure pay-per-mile beats every other model, since paying by the mile can be cheaper than paying a flat rate for a car that rarely moves.
Exactly What Driving Data Insurers Collect
Standard telematics programs collect miles driven, speed, hard braking events, rapid acceleration, cornering force, and time-of-day patterns. State insurance regulators, including the Washington Office of the Insurance Commissioner, confirm insurers may combine this behavioral data with traditional rating factors like your driving record rather than replacing them outright.
Here’s the fuller breakdown of what typically gets tracked, and what’s often optional:
Mileage — nearly universal across every program type.
Speed relative to posted limits — standard in behavior-scored programs.
Hard braking and rapid acceleration — the two metrics most programs weight heaviest.
Time of day — late-night driving usually scores worse regardless of how smoothly you drive.
Phone handling while moving — increasingly common as a distracted-driving proxy.
GPS/location data — collected by many but not all programs, and sometimes an optional toggle.
One program covering the data landscape put it plainly: usage-based programs often layer in engine diagnostics and driver-assist system signals beyond the basics, building a more detailed profile than most drivers assume.
Statistic Callout: The NAIC confirms that many telematics programs collect GPS or location data alongside core driving metrics, though location tracking is more often a program feature than a universal requirement across every insurer.
What these programs generally don’t do is record cabin audio or video. That misconception shows up constantly in reader questions, but standard telematics products are built around motion and location sensors, not microphones or cameras. If a program ever asks for cabin recording, that’s a meaningfully different product than typical usage-based insurance, and worth extra scrutiny.
Benefits: Who Saves and How Much You Can Expect
Telematics tends to lower premiums for low-risk, low-mileage drivers who already drive during daylight hours and brake smoothly. It doesn’t tend to help much beyond that group, and it’s not designed to.
Statistic Callout: Consumer Reports surveyed 40,566 U.S. policyholders and found the median annual savings from telematics was $120, with younger drivers and households that include a young driver often seeing larger discounts than that median figure.
Some drivers do hit those higher tiers, but the middle of the distribution is much closer to $120 a year than to a headline-grabbing percentage. Our own breakdown of how telematics savings actually get calculated walks through why advertised maximums rarely apply to the average enrollee.
Savings aside, the programs offer value that doesn’t show up on your bill:
Real-time feedback on braking and speed habits functions like a driving coach, which some drivers use to genuinely change behavior.
Younger drivers, who typically pay the highest base premiums, often see proportionally larger discounts once they can prove safe habits independent of age-based assumptions.
Low-mileage households finally get pricing that reflects actual road exposure instead of a flat annual estimate that assumes everyone drives the same amount.
Drawbacks and Privacy Risks: What Could Go Wrong
Telematics can raise your premium just as easily as it lowers it, and it can expose more personal data than most drivers expect going in. The NAIC is explicit that monitoring can reveal risky behavior, and insurers aren’t obligated to only reward good habits. They can penalize bad ones too.
The concrete risks worth weighing before you enroll:
Rate increases. If your measured braking, speed, or late-night driving looks worse than your insurer’s baseline assumption, your renewal price can go up, not down.
Data sharing and sale. Some insurers reserve the right to share de-identified or aggregated location data with third parties, and privacy specialists warn this remains a real concern even when data is technically anonymized.
Breach exposure. Continuous location tracking creates a detailed record of where you go and when. If that dataset is ever breached, it’s a far more revealing leak than a stolen credit card number.
Driver misattribution. If your teenager, partner, or a coworker drives your car regularly, their habits can drag down a score you thought reflected only your own driving.
Pro Tip: Ask specifically whether your insurer sells or shares de-identified location data with third parties, and get the answer in writing rather than relying on a verbal assurance from a call center rep. Privacy policies covering telematics are often vaguer than the rest of the contract.
There’s also a timing trap. Because most programs need several months of monitoring before calculating any adjustment, signing up right before a renewal you’re hoping to lower probably won’t help. The discount, if there is one, shows up on the cycle after monitoring completes, not the one you’re currently paying.
Is Telematics a Good Fit for You? A Short Checklist
Telematics tends to help drivers who log fewer than roughly 8,000 to 10,000 miles a year, avoid late-night trips, and already brake gradually rather than sharply. If that’s not you, the upside shrinks fast.
Run through this before deciding:
Do you drive under 10,000 miles annually?
Is most of your driving during daylight hours rather than late night or early morning?
Do you already avoid hard braking and rapid acceleration in normal traffic?
Is your current premium already on the higher side, giving more room for a discount to matter?
Does anyone else regularly drive your car, and would their habits skew your score?
Are you comfortable with an insurer knowing your regular routes and destinations?
Do you need savings fast, or can you wait several months for a monitoring period to complete?
If you drive for work, cover long highway commutes, work night shifts, or simply don’t want a company tracking your location, telematics is less likely to help you and more likely to feel invasive for the return you’d get.
How to Enroll, How Long Monitoring Lasts, and Whether You Can Opt Out
Enrollment happens through your insurer’s app or website, and most programs require a multi-month monitoring window before any discount applies. Here’s the typical sequence:
Enroll online or through your carrier’s app, selecting either a smartphone-based program or requesting an OBD-II device by mail.
Drive normally during the monitoring period, usually somewhere between 60 and 90 days depending on the insurer, though some programs extend this to several months.
Receive your adjusted rate, applied either at your next monthly billing cycle (behavior-based programs) or at renewal (mileage-based programs).
Continue monitoring or opt out, depending on whether the program runs continuously or only during an initial evaluation window.
A few practical wrinkles come up often. If someone else drove your car during monitoring and it hurt your score, most insurers let you flag specific trips for review, though the process varies by carrier and isn’t always fast. If you opt out mid-program, some insurers simply revert you to your prior rating factors, while others treat the discount as forfeited for that policy term. And if you’re financing a new home purchase alongside a new vehicle, it’s worth checking with whoever coordinates your insurance rate factors before assuming telematics savings will offset a broader premium increase tied to other market pressures.
How Insurers Use Telematics Data for Claims and Pricing
Telematics data doesn’t only set your price. Depending on your policy terms, it can also become evidence after an accident, which is a detail many drivers never think about until they’re in a dispute.
The legitimate, disclosed uses generally include:
Underwriting and renewal pricing, the core function most drivers expect.
Claim reconstruction, where speed and braking data from the moments before a crash can support or contradict a driver’s account of what happened.
Fraud detection, flagging inconsistencies between a claimed accident scenario and recorded vehicle behavior.
Aggregated analytics, where de-identified data across many drivers gets sold or licensed to research firms, automakers, or other third parties.
Pro Tip: Ask your insurer three specific questions before enrolling: how long is telematics data retained after you leave the program, can that data be used against you in a claims dispute, and is any data sold or shared even in de-identified form? Get the answers in the actual policy document, not just a sales conversation.
Consumer advocates consistently recommend calling your insurer directly when privacy language in a policy feels vague, since telematics addenda are often written more loosely than the rest of the contract. If you’re weighing how a recorded accident might interact with other coverage types, it’s worth reviewing how uninsured motorist claims typically get processed alongside any telematics-based evidence.
How an Independent Broker Helps You Evaluate Telematics Programs
An independent broker can compare telematics offers across multiple carriers at once, something you simply can’t do by requesting one quote at a time from individual insurance companies. That’s the core value: instead of evaluating one insurer’s program in isolation, a broker cross-references several carriers’ telematics terms, savings potential, and privacy language side by side.
In practice, that means a broker will:
Shop your driving profile across more than 20 carriers to see which telematics program actually fits your mileage and habits.
Read the fine print on data retention and sharing clauses so you don’t have to parse insurance legalese yourself.
Estimate a realistic savings range for your situation rather than quoting an advertised maximum that rarely applies broadly.
Step in if a household driver’s habits get misattributed to your score, helping you request a correction from the carrier.
A driver comparing telematics programs across carriers often finds one insurer’s “up to 30%” advertised discount translates to something much closer to the Consumer Reports median of $120 a year once their actual mileage and driving pattern get scored. A broker’s job is catching that gap before you enroll, not after your first renewal disappoints you.
Statistic Callout: With median telematics savings landing around $120 annually, the real value of shopping multiple carriers isn’t finding the one with the flashiest advertised discount. It’s finding the carrier whose specific scoring model actually rewards your driving pattern.
Author Perspective: Honest Pros and Cons From a Broker’s Viewpoint
Telematics is a useful tool for a specific type of driver, not a universal upgrade over traditional pricing, and treating it as a guaranteed discount is where most people get disappointed.
The gap that matters most isn’t between telematics and traditional insurance. It’s between what the marketing promises and what the median driver actually experiences. The upside is real for genuinely low-mileage, low-risk drivers. For everyone else, it’s a modest discount attached to a meaningful amount of ongoing data collection, and that trade deserves more scrutiny than most enrollment flows encourage.
A few things worth doing before you commit:
Treat the first monitoring period as a trial, not a commitment, and actually read your mid-program scoring reports if your insurer provides them.
Ask pointed questions about data retention and third-party sharing before you enroll, not after you’ve already handed over months of location history.
Use the driving feedback as a coaching tool even if the discount ends up smaller than advertised. That part has real value regardless of the payout.
If you’re genuinely uneasy about location tracking, ask whether a mileage-only program is available instead of full behavior-based monitoring.
State rules on telematics data protection and consumer disclosure vary, so a program that’s straightforward in one state can carry different fine print in another. When the details get complicated, that’s exactly when a conversation with a broker who can compare carrier-specific terms is worth more than another hour of reading marketing pages.
How South Lake Agency Can Help You Evaluate Telematics Options
We can run a side-by-side comparison of telematics pricing against traditional rating for your specific driving profile, using quotes from more than 20 carriers instead of just one insurer’s self-reported estimate.
That’s the practical difference between shopping telematics on your own and shopping it through South Lake Agency Insurance Brokers. Going carrier by carrier means reading each program’s privacy terms yourself and hoping the advertised discount matches your actual driving pattern. We do that comparison for you, and because we don’t charge broker fees, there’s no added cost layered onto whatever premium you land on. Our services here include:
Comparing telematics program terms and expected discounts across our full carrier network.
Reading privacy and data-sharing clauses so you know exactly what you’re agreeing to before enrolling.
Helping correct driver-attribution issues if a household member’s habits affected your score.
Supporting you through claims involving telematics data, so you’re not navigating that conversation with your insurer alone.
If you’re ready to see how a telematics program compares to your current rate, get a personalized auto insurance quote and we’ll walk you through which carriers’ programs actually fit your mileage and driving pattern. You can also start a quote online in a few minutes if you’d rather begin there.
Sources
For state-specific consumer protection questions, your state insurance commissioner’s office is the most reliable place to confirm current rules, since telematics regulations aren’t identical everywhere.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
Recommended
Comments