



How Much Umbrella Insurance Do You Actually Need?

Start with at least enough umbrella coverage to protect your net worth. For most people, that means a $1M policy. If your assets, income, or liability exposure exceed typical thresholds, you may need more than the baseline coverage; some situations warrant higher limits.
Here’s the quick version:
$1M limit: Recommended starting point for most households. Kiplinger calls this the baseline for most people.
$2M–$5M: Consider this range if your net worth exceeds $1M, you own rental properties, have teenage drivers, or run a business from home.
$5M+: High-net-worth individuals, professionals with significant public exposure, or anyone with multiple high-risk assets.
Typical annual premiums (approximate):
Coverage Limit | Estimated Annual Premium |
$1M | $200–$500 |
$2M | $250–$300 |
$5M | Low hundreds |
These figures reflect NerdWallet’s reporting that $1M policies often start in the low hundreds per year, with each additional million costing progressively less.
Before you call anyone, run through three quick checks: confirm your auto liability is at least $250,000–$300,000, total your non-retirement assets, and note any high-risk activities or properties. Then contact South Lake Agency Insurance Brokers for a personalized quote across 20+ carriers.
Key Takeaways
Umbrella insurance is one of the most cost-efficient ways to protect your net worth: a $1M policy typically costs $200–$500 per year and covers liability claims that would otherwise come directly out of your assets.
Point | Details |
Start with $1M | Most households need at least $1M; match the limit to your total exposed net worth. |
Check underlying limits first | Carriers require $250k–$300k auto and $300k homeowners liability before issuing an umbrella. |
Premiums are lower than expected | $1M coverage typically runs $200–$500 per year; each additional million costs progressively less. |
Exclude ERISA plans, review IRAs by state | 401(k) and 403(b) assets are federally protected; IRA protection depends on your state’s law. |
South Lake Agency shops 20+ carriers | No broker fees. |
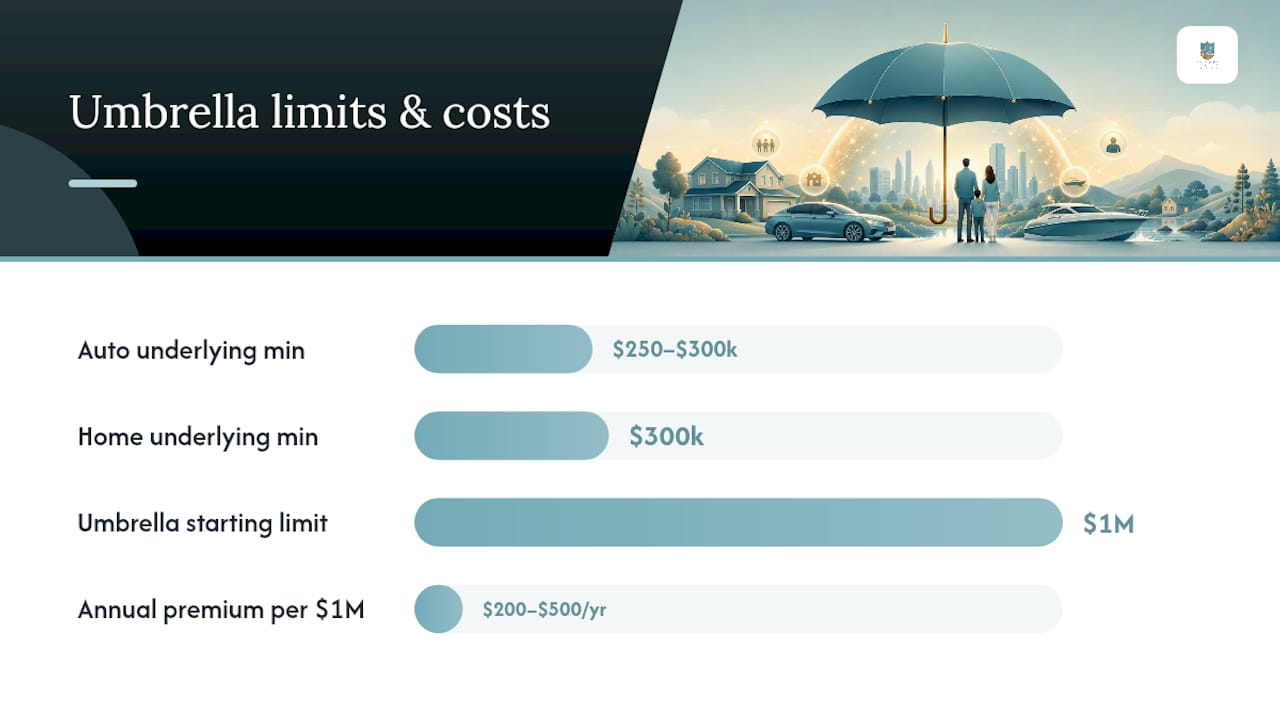
Table of Contents
What is umbrella insurance and how does it work?
Umbrella insurance is a personal liability policy that pays claims after your underlying auto or homeowners coverage runs out. It does not replace those policies. It sits above them.
Core coverages typically include:
Bodily injury liability: Medical bills, lost wages, and pain-and-suffering claims from accidents you cause.
Property damage liability: Damage you cause to someone else’s property.
Personal liability: Libel, slander, false arrest, and invasion of privacy claims.
Worldwide coverage: Many personal umbrella policies extend protection globally, not just in the U.S.
How the attachment point works
Every umbrella policy has an attachment point, the dollar threshold at which it kicks in. If your auto policy pays up to $300,000 and a jury awards $750,000, your umbrella covers the remaining $450,000 (minus any applicable deductible or retained limit). Defense costs, including attorney fees, are typically covered on top of the liability limit, not subtracted from it.
Umbrella vs. excess liability: Both add limits above your primary policy, but they are not the same. An umbrella policy carries its own insuring agreement and can “drop down” to cover claims your underlying policy excludes entirely. Excess liability simply extends the same limits and terms as the underlying policy, nothing more. Arvori’s coverage breakdown explains this distinction clearly: umbrella is broader; excess is cheaper but narrower.
Quick scenario: You rear-end another driver at highway speed. Medical bills, lost wages, and the lawsuit total $620,000. Your auto policy covers $300,000. Without an umbrella, you pay $320,000 out of pocket. With a $1M umbrella, you pay nothing beyond your auto deductible.
Who actually needs umbrella insurance?
Anyone with assets worth protecting and any meaningful liability exposure should take this seriously. That covers more people than most realize.
Risk signals that put you in the high-priority group:
Net worth above $300,000 in non-retirement assets
A home with a pool, trampoline, or dog
Teenage or young adult drivers on your policy
Rental properties (even one)
A boat, jet ski, ATV, or motorcycle
Frequent hosting of guests or events at your home
A side business or home-based business
A public-facing professional role or significant social media presence
Practical income and asset thresholds to keep in mind:
If your liquid assets (savings, taxable investments, home equity) exceed $250,000, a single serious lawsuit can threaten a meaningful portion of your wealth.
If your household income exceeds $150,000 annually, a plaintiff’s attorney may pursue future wages in a judgment, not just current assets.
If you own multiple vehicles or properties, your exposure multiplies with each one.
Two scenarios where umbrella coverage pays off fast:
A guest slips on your icy driveway and suffers a traumatic brain injury. Medical costs and the resulting lawsuit reach $800,000. Your homeowners liability limit is $300,000. The remaining $500,000 comes from you, unless you have an umbrella.
A teenage driver on your policy causes a multi-car accident. Total damages: $1.1M. Your auto policy covers $300,000. A $1M umbrella absorbs the rest and covers your legal defense.
How do you calculate how much umbrella coverage you need?
The most reliable method is to match your coverage limit to your total exposed net worth, then add a buffer. Fidelity recommends using net worth as the primary input, excluding ERISA-protected employer plans from the calculation since those assets carry federal creditor protection.
Step 1: List your exposed assets
Add up everything a plaintiff could potentially reach:
Home equity (current market value minus mortgage balance)
Vehicles (market value)
Taxable investment accounts and brokerage accounts
Savings and checking accounts
Second homes, vacation properties, or rental properties
Step 2: Decide how to handle IRAs
Unlike 401(k) and 403(b) plans, which are shielded from creditors under ERISA federal law, IRA protections vary by state. In Minnesota, IRAs have strong but not unlimited protection. If you live in a state with weaker IRA protections, include those balances in your exposed-asset total.
Step 3: Add a forward-looking buffer
Your assets today are not your only exposure. A court can garnish future wages. Add one to three years of gross income to your asset total if you are a high earner or in a profession with elevated lawsuit risk (medicine, law, real estate, contracting).
Step 4: Round up to the next $1M increment
Umbrella policies are sold in million-dollar increments. Round your total up, not down.
Worked example:
Conservative choice: $1M umbrella (covers exposed assets with a $425,000 buffer). Aggressive choice: $2M umbrella (adds a forward-looking income buffer for a dual-income household earning $180,000/year).
Pro Tip: Before assuming your umbrella will attach, verify your underlying auto and homeowners limits. If your auto policy only carries $100,000 in liability, most carriers will not issue an umbrella until you raise it to at least $250,000–$300,000. That underlying upgrade costs money too, so factor it into your total budget.
How much does umbrella insurance typically cost?
The price is lower than most people expect, and that is not marketing language. Fidelity notes that umbrella premiums are relatively low because payouts are statistically rare. The policy only activates after primary limits are exhausted, which keeps the insurer’s risk manageable.
NerdWallet reports that $1M umbrella policies often start in the low hundreds of dollars per year, with each additional million costing progressively less; a $2M policy does not cost twice a $1M policy.
Factors that move your premium up or down:
Driving record: At-fault accidents and moving violations raise rates significantly.
Number of vehicles and drivers: More cars and younger drivers mean higher exposure.
Claims history: Prior liability claims on any underlying policy will increase your umbrella premium.
Location: States with higher litigation rates or jury awards tend to produce higher premiums.
Underlying limits: Carriers that require higher underlying limits reduce their own risk, which can lower the umbrella premium.
Occupation and public profile: Some professions or high-visibility roles attract higher premiums.
Property count: Each additional home, rental, or recreational vehicle adds exposure.
Sample premium ranges by profile:
Profile | Estimated Annual Premium |
Single homeowner, clean record, 1 vehicle | $200–$300 |
Married couple, 2 vehicles, 1 teen driver | Low hundreds |
Homeowner with rental property, boat | Low hundreds |
High-net-worth household, multiple properties | Low hundreds |
These are illustrative ranges. Your actual quote depends on your specific carrier, underlying limits, and risk profile.
What does umbrella insurance not cover?
Knowing the exclusions matters as much as knowing the coverages. A few gaps catch people off guard.
Standard exclusions in most personal umbrella policies:
Intentional acts: Deliberate harm you cause is not covered.
Business liability: Claims arising from business operations are excluded unless the business is specifically scheduled on the policy.
Professional liability (E&O): Errors and omissions in professional services require a separate policy.
Contractual liability: Obligations you assume under a contract are generally excluded.
Workers’ compensation: Injuries to employees are not covered under a personal umbrella.
Damage to your own property: Umbrella is a liability product. It does not cover your own losses.
Punitive damages: Some states prohibit insuring punitive damages as a matter of public policy.
When umbrella “drops down” and when it does not
An umbrella can drop down to cover a claim your underlying policy excludes, but only if the umbrella’s own insuring agreement covers that type of claim. When it does drop down, many policies impose a retained limit, essentially a self-insured gap you pay before the umbrella responds. Personal umbrella retained limits are typically modest, but commercial umbrellas can carry retained limits of $10,000–$25,000 per Arvori’s analysis.
Spotting gaps before you buy: Ask your agent whether your umbrella covers watercraft, rental properties, and home-based business activities. If any of those apply to you and the answer is no, you need either a scheduled endorsement or a separate policy. A general liability policy is often the right solution for rental property or side-business exposure.
How do you buy umbrella insurance and what do carriers require?
Buying umbrella coverage is straightforward, but there is a specific sequence that prevents surprises.
Step 1: Check your underlying liability limits
Most carriers require at minimum $250,000–$300,000 in auto liability and $300,000 in homeowners liability before they will issue a $1M umbrella. If your current limits are lower, you must raise them first. NerdWallet confirms that this underlying upgrade can increase your base premiums, so budget for both changes together.
Step 2: Inventory all properties and vehicles
Every home, rental unit, vehicle, boat, ATV, and motorcycle needs to be disclosed and scheduled. Gaps in the schedule create gaps in coverage.
Step 3: Get a bundled quote
Carriers often discount umbrella policies when they also write your auto and homeowners coverage. South Lake Agency Insurance Brokers shops across 20+ carriers simultaneously, which means you see the bundled and standalone options side by side.
Step 4: Confirm the schedule of underlying policies
The umbrella carrier will verify that your underlying policies are active and meet minimum limits at placement and at every renewal. A lapse or reduction in underlying limits can leave you exposed even if the umbrella is technically in force.
Questions to ask your agent before signing:
Does this policy drop down if my underlying policy excludes a claim?
What retained limit applies when it drops down?
Which underlying policies are scheduled, and what happens if I change carriers mid-term?
Are defense costs paid inside or outside the liability limit?
Does the policy cover claims arising from my rental property or home-based business?
Red flags to watch for:
Unusually high retained limits on a personal umbrella (anything above $5,000 deserves an explanation)
Carriers that exclude watercraft or recreational vehicles without offering an endorsement
Policies that do not cover defense costs on top of the liability limit
Is umbrella insurance worth the cost?
For most people with any meaningful assets, yes, by a wide margin.
A $1M umbrella policy costs roughly $200–$500 per year. That is $17–$42 per month to protect hundreds of thousands of dollars in assets from a single lawsuit. The math is hard to argue with.
Where it clearly pays:
You have a net worth above $200,000 in exposed assets
You have teenage drivers, a pool, a dog, or a rental property
You host guests regularly or have a high public profile
You want defense costs covered without depleting your liability limit
Where it may be lower priority:
Your net worth is minimal and your income is modest
You rent your home, have no vehicles, and have no high-risk activities
Your state provides strong homestead and IRA exemptions that shield most of your assets
Even in the lower-priority scenario, the annual cost is low enough that most financial planners still recommend at least a $1M policy once you have any assets to protect.
The real value of umbrella insurance is not just the payout. It is the legal defense. A serious liability claim generates attorney fees, expert witnesses, and court costs long before a settlement is reached. Those costs can exceed $100,000 on a case that ultimately settles for less than your primary policy limit. An umbrella covers that defense spending on top of the liability limit, not instead of it.
How South Lake Agency helps you get the right umbrella policy
South Lake Agency Insurance Brokers shops umbrella coverage across 20+ top-rated carriers with no broker fees charged to clients.
The brokerage’s process is built around comparison, not convenience. Agents review your underlying auto and homeowners limits, identify any gaps in your schedule of policies, and present options from multiple carriers so you see real price differences, not a single take-it-or-leave-it quote. Over 337 five-star reviews reflect that consistency.
What the process looks like:
Review your current auto and homeowners liability limits
Identify any properties, vehicles, or activities that need to be scheduled
Shop 20+ carriers for bundled and standalone umbrella options
Coordinate with lenders if you are in a new home purchase
Follow up at renewal to confirm underlying limits remain in compliance
Pro Tip: Ask your South Lake Agency agent to run the umbrella quote alongside your auto and homeowners renewal at the same time. Bundling all three through a single carrier often produces a lower combined premium than buying the umbrella separately.
South Lake Agency serves clients across Minnesota and select Midwest states. Readers in the Minnesota area can connect with a local agent in Saint Louis Park for in-person support.
The case for matching your limit to your net worth, not a round number
Most people pick $1M because it sounds like a lot. That instinct is not wrong, but it is incomplete.
The right limit is not a round number. It is the number that covers your specific exposed assets plus a forward-looking buffer for future income. A household with $800,000 in exposed assets and two high earners should not stop at $1M just because that is the default. The incremental cost of going from $1M to $2M is often $75–$150 per year. That is a small price for doubling the protection on a significant asset base.
Two signals that should prompt an immediate broker conversation: your net worth has grown substantially in the past two years, or you have taken on new liability exposure (a rental property, a teenage driver, a home renovation that added a pool). Both situations change your risk profile faster than most people update their coverage.
Life events that should trigger a policy review: buying or selling a home, adding a driver to your auto policy, starting a side business, receiving an inheritance, or retiring and shifting from wage income to investment income. Each one changes either your asset exposure or your income garnishment risk.
Get a personalized umbrella quote with no broker fees
Comparing umbrella policies across carriers on your own takes hours and still leaves you guessing whether the underlying limits are right. South Lake Agency Insurance Brokers does that work for you, at no cost.
Request a quote through South Lake Agency’s umbrella insurance page and an agent will review your current auto and homeowners limits, identify any scheduling gaps, and present options from 20+ carriers side by side. No broker fees. No obligation. Before you request the quote, pull your current auto policy and homeowners policy declarations pages so your agent can confirm your underlying limits meet carrier minimums from the first call.
Sources
The following sources informed the figures, calculation methods, and coverage guidance in this article:
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
Recommended
Comments